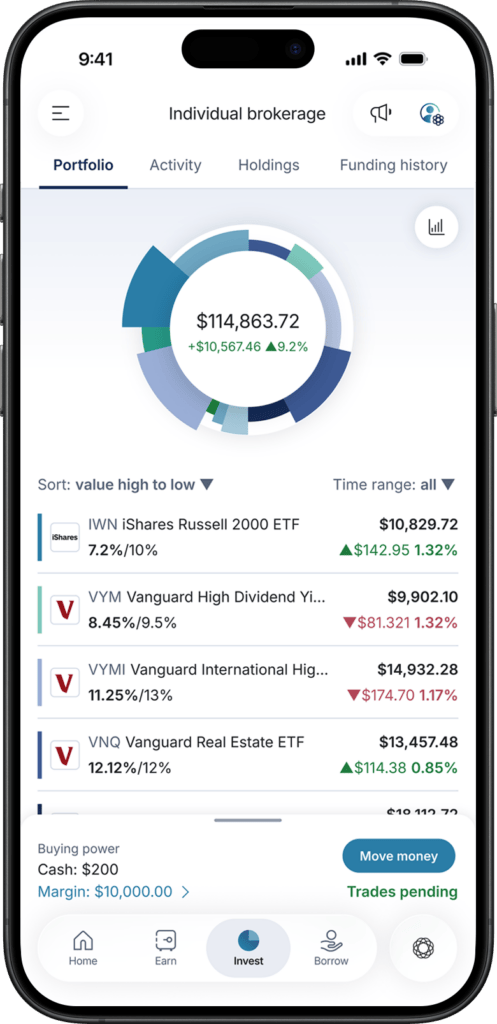
M1 RETIREMENT ACCOUNTS

Plan your retirement with advice built in

The journey to retirement doesn’t have to be a chore. Open an M1 IRA, automate your contributions, and tap M1 Advisor for guidance along the way.

Fiduciary advice 24/7

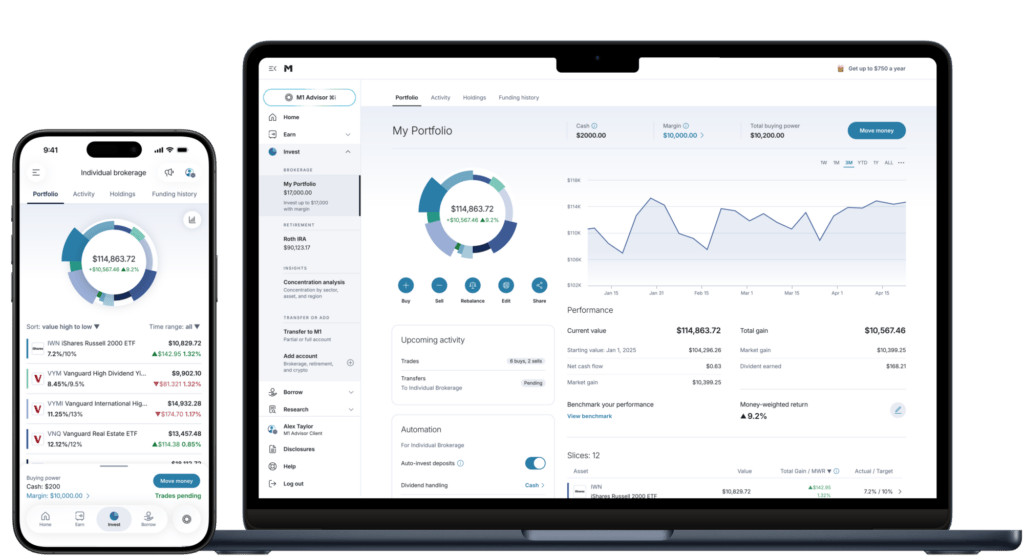
Retirement planning isn’t easy. M1 Advisor can help. Advice comes from an SEC-registered investment adviser, so it’s required to act in your best interest by law. You can stress-test your retirement plan, connect external 401(k)s, and build confidence in your retirement outlook.

Build your nest egg, your way

How much are fees really costing you?

High-cost holdings, management fees, and forgotten 401(k)s can erode your retirement growth. See the potential impact with M1’s new Compounding Cost Calculator. It’s free to use and only takes a few minutes.

Move your retirement account to M1

Manage your accounts in one place.

Have a 401(k) from an old job? Or maybe a few? Moving your employer-sponsored retirement plan into an M1 IRA lets you keep the tax advantages of your old account.

If you want to consolidate and manage your portfolio in M1, we make it easy to track your progress. It only takes a few steps to transfer an IRA from another brokerage to M1.

A rollover is not your only option. Talk to a financial expert before making changes to your retirement savings.

Which IRA is right for you?

An individual retirement account (IRA) is an investment account that can help you save money for retirement with tax-free growth or on a tax-deferred basis. M1 offers 3 types of IRAs.

Traditional IRA

Contributions to a Traditional IRA are usually tax-deductible. If you contribute pre-tax, you’ll need to pay taxes on your contributions and earnings later, when you withdraw from this account.

Roth IRA

Contributions to a Roth IRA are not tax-deductible. But when it’s time to withdraw, you’ll be able to put every qualified dollar to use, tax-free.

SEP IRA

SEP (Simplified Employee Pension) IRAs are available to those who are self-employed, own a business, employ others, or earn freelance income. You may need to pay taxes on funds you withdraw from this account.

Use time to your advantage

Investing for retirement sooner, rather than later, can help you compound your earnings.

Hypothetical example for illustrative purpose only. Calculations assuming the following constraints: (a) an initial investment of $1000, (b) an annual rate of return of 10%, (c) no taxes, fees, inflation, or withdrawals. The assumed rate of return is not guaranteed as investing involves risk of loss. Source: Investopedia.com

Your retirement account questions, answered

Have a question that isn’t listed here? Go to the Help Center. 

M1 offers Traditional, Roth and SEP IRAs, plus inherited (beneficiary) Traditional and Roth IRAs. You can hold one Traditional and one Roth IRA at M1. SEP IRAs are for self-employed individuals only; M1 doesn’t support SEP plans that cover employees. M1 doesn’t offer SIMPLE or Spousal IRAs. IRAs take $500 to open, and after that you can deposit $10 or more at a time. 

With a Traditional IRA, contributions may be tax-deductible, and you pay income tax on withdrawals in retirement. With a Roth IRA, you contribute after-tax dollars, and qualified withdrawals are tax-free. Roth IRAs also have no required minimum distributions during the original owner’s lifetime. Compare Traditional and Roth IRAs.

Anyone with earned income can contribute to a Traditional IRA, up to the annual limit or their earned income for the year, whichever is less. Roth IRA eligibility depends on income. For 2026, the ability to contribute to a Roth IRA phases out between $153,000 and $168,000 of modified adjusted gross income for single filers, and between $242,000 and $252,000 for married couples filing jointly.

For 2026, you can contribute up to $7,500 across all your Traditional and Roth IRAs combined, or $8,600 if you’re 50 or older. SEP IRA contributions are capped at the lesser of 25% of compensation or $72,000.

Yes. You can roll over an old 401(k), 403(b) or 457(b) into an M1 IRA: pre-tax money into a Traditional IRA, and Roth money into a Roth IRA. You start the process by requesting a direct rollover from your plan administrator; M1 can’t initiate it for you. A rollover isn’t your only option. You may also be able to leave the money in your old plan or move it to a new employer’s plan, and each choice carries different costs and protections. M1 Advisory Services LLC doesn’t act as an ERISA fiduciary, including on rollover decisions. See how to roll over a 401(k) to M1.

Yes. M1 supports Roth conversions, the step used in a backdoor Roth strategy. Cash conversions from a Traditional IRA to a Roth IRA can be done in the app and usually process in 1–2 business days. The converted amount is generally taxable in the year of the conversion, and a conversion can’t be reversed. M1 doesn’t provide tax advice, so consider talking with a tax professional first. Learn more about backdoor Roth IRAs. 

M1 Advisor is the fiduciary AI financial advisor built into M1’s AI wealth management platform. It generates personalized investment recommendations based on your goals, risk tolerance and financial situation, and it can factor in balances from outside accounts you link, like an old 401(k). You can ask it questions like when you might be able to retire or how much you may need. M1 Advisor is non-discretionary so it doesn’t place trades on your behalf – acting on a recommendation is up to you. M1 Advisor is offered by M1 Advisory Services LLC, a separate SEC-registered investment adviser that acts as a fiduciary to its advisory clients. M1 Advisor is included at no additional cost to M1 clients through December 31, 2027.

Generally, yes, if you withdraw before age 59½. Early withdrawals from a Traditional IRA are usually taxed as income and may carry a 10% additional tax, though the IRS allows some exceptions. Roth IRA contributions can be withdrawn at any time without tax or penalty. Roth earnings are tax-free only for qualified withdrawals, generally after age 59½ and once the account has been open for five years. M1 doesn’t provide tax advice, so consider talking with a tax professional first.

M1 IRAs can hold U.S.-listed stocks and ETFs, with fractional shares and the same Pie-based investing as M1 brokerage accounts. A Crypto Account can’t be held as an IRA, but some crypto-related ETFs and trusts can be held in an M1 IRA. Margin isn’t available in IRAs. 

M1 charges a $3 monthly fee to access the platform, billed as either a Platform Fee or an IRA Fee depending on your accounts. It’s waived in any 30-day billing cycle where your total M1 assets reach $10,000 for at least one day, and it’s never more than $3 a month no matter how many accounts you have. There are no commission, trading or management fees, and M1 Advisor is included at no additional cost through December 31, 2027. Other fees may apply. See M1’s Fee Schedule.

Invest in your retirement with advice for every step

SAIF-01222025-tbyjlvse