M1 Advisor: your financial life finally has a CFO


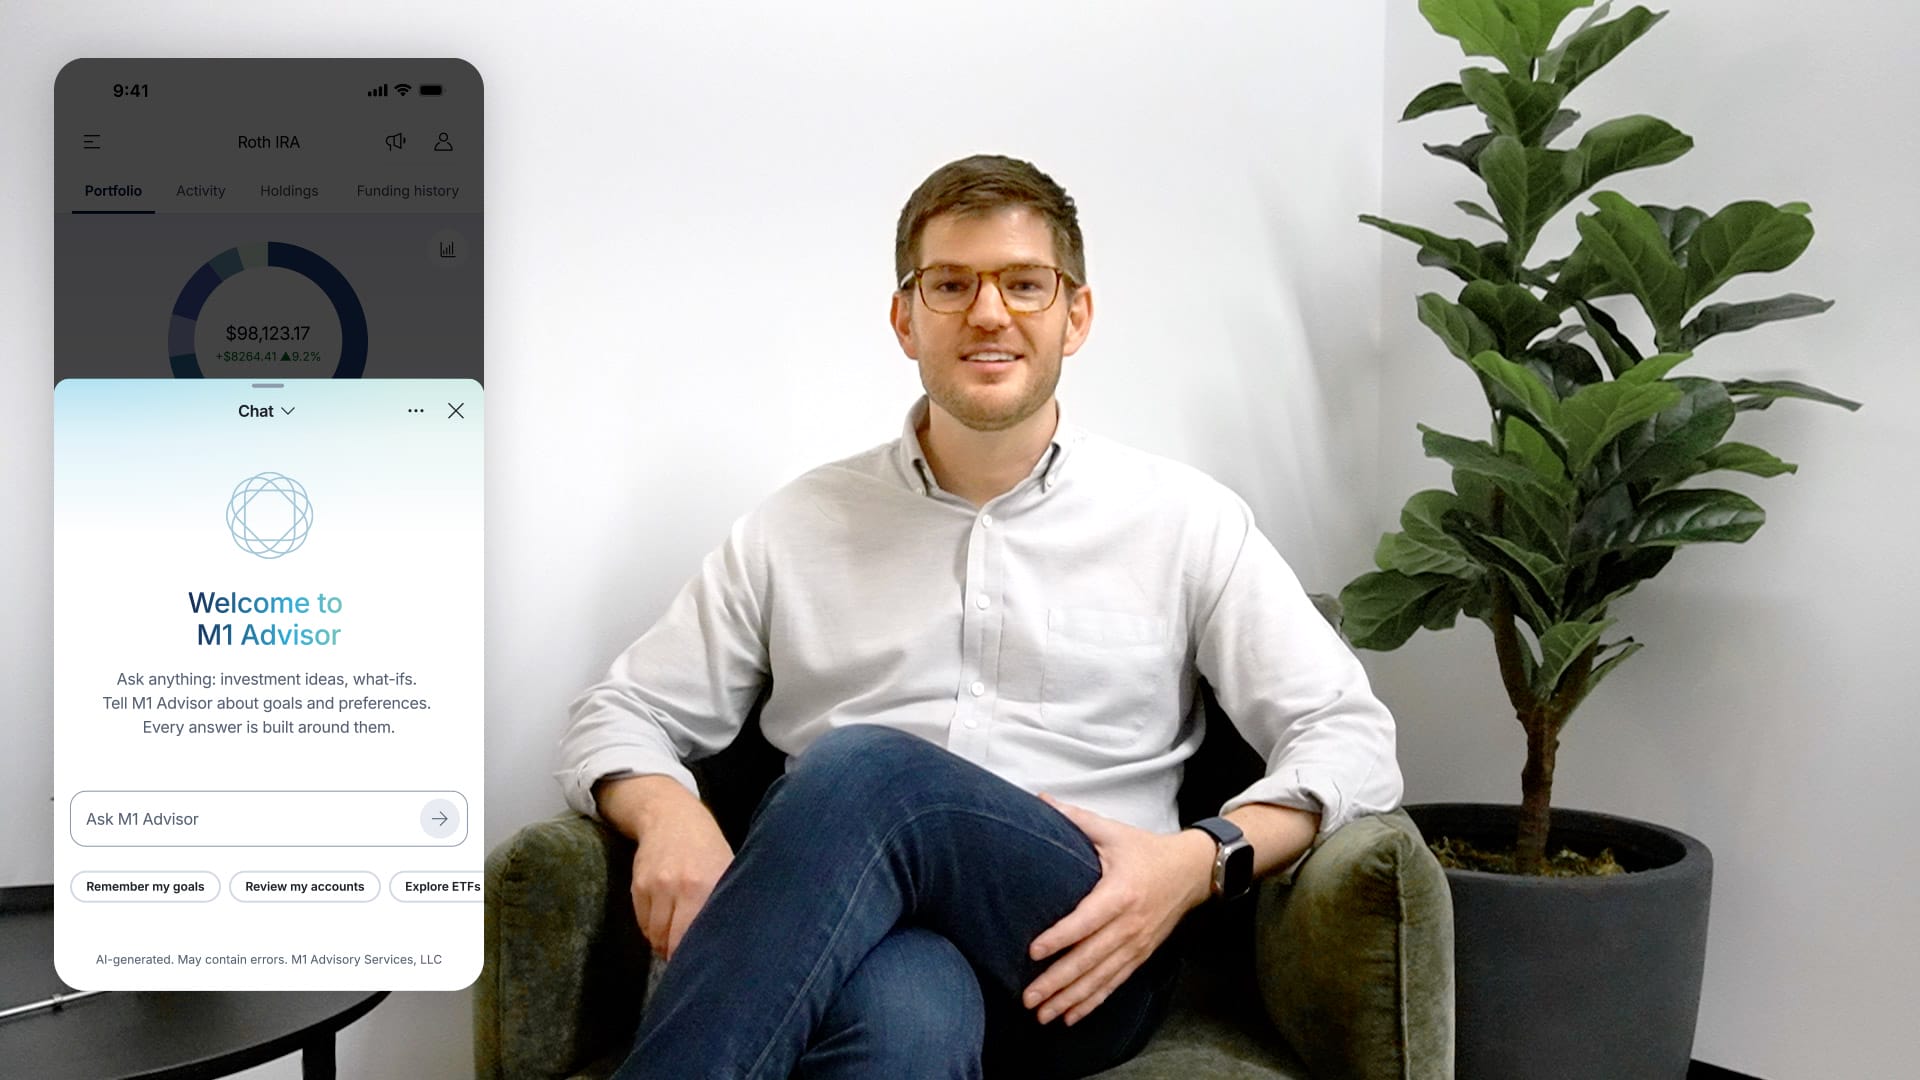
An AI financial advisor built into M1, offered through an SEC-registered investment adviser. Live now for M1 clients, and free through the end of 2027.
Today we’re launching M1 Advisor, an AI financial advisor built into M1.
You can talk with it about your money any time, day or night, and it works with you to help manage and build your wealth. It gets to know you better over time and can read information from your Invest, Cash, and Borrow accounts, so its advice is specifically tailored to you. You now have an expert on call for one of the most complicated and consequential parts of your life.
It’s offered through M1 Advisory Services, an SEC-registered investment adviser with a legal duty to act in your best interest. It’s free for M1 clients through December 31, 2027.
Why financial advice matters
Think about the most important moments in life. The job offer in another city. The first home. A child’s education. The business you’ve always wanted to start. A parent who needs your help. The day you decide you’ve worked long enough. Every one comes with hard, emotional decisions. And every one is also a money decision that shapes the life that comes after it.
Now think about what each of those moments asks of you. RSU vesting schedules, 401(k) rollovers, and state income tax. PMI, escrow, fixed vs. ARM, and whether to buy points. 529 plans and the FAFSA. S-corp elections, self-employment tax, and the QBI deduction. Powers of attorney and long-term care insurance. Roth conversions, RMDs, and sequence-of-returns risk. Each one is its own field of expertise, with its own rules, its own exceptions, and its own expensive mistakes. No one is born knowing this stuff, and almost no one is taught it.
To further complicate things, every decision touches the others. Pay down the mortgage, and you have less to invest. Sell a winning stock for the down payment, and you may owe taxes. Hold too much cash, and inflation chips away at it; hold too little, and one surprise becomes a crisis. Then your income changes, the markets move, the tax rules shift, and the right answer moves with them.
Most people are too busy with the chores of money to learn what smart decisions require. Opening accounts, paying bills, and placing trades crowd out everything else. What’s left is a nagging sense that you should be doing more, with no time to figure out what or how.
The wealthy don’t have this problem. They have a financial institution that handles most of the chores, and they pay experts to answer their questions, guide their decisions, and see the whole picture. With that help in place, the question stops being “am I doing this right?” and becomes “what do I want my money to make possible?” For generations, that kind of expertise cost tens or even hundreds of thousands of dollars a year, so only a few families ever had it.
Everyone else has had a search bar, a brother-in-law with opinions, and a lot of guessing.
What the index fund did for investing
Investing used to be gated to the wealthy.
Before the index fund, the usual way to own a diversified portfolio was a mutual fund run by professional stock pickers. These funds carried significant fees: fees on the way in, fees while it sat, and fees on the way out. The fees were the price of access to investing experts, and they took a big bite out of returns.
Fifty years ago, in 1976, Jack Bogle built a fund around a simple but groundbreaking idea. Every market has an average return, and the average investor earns that return minus the fees they pay. So you could come out ahead of the average investor just by owning the whole market and keeping your fees low. It was the first index fund for everyday investors.
Today, index funds hold $22.4 trillion, more than the $18.9 trillion in actively managed funds. Because they charge so little, roughly $100 billion a year stays with investors instead of going to fund managers.¹ Most important, the compounding engine of the markets is no longer reserved for the wealthy. Anyone can take part.
The index fund brought down the cost of a portfolio, access surged, and people’s finances were better off for it. I believe the same thing is about to happen with financial advice. AI has sent the cost of expertise plummeting. Access is going to surge, and people’s finances will be better off for it.
And this time, it reaches further. The index fund touches only your investments; financial advice touches every financial decision you will ever make.
An expert in your corner
Starting today, M1 clients have an expert of their own.
M1 Advisor sees the whole picture. Because it works from your actual accounts, its advice starts from your real numbers and weighs how each move affects the rest. Ask it anything, in your own words:
- “I have a large tax bill due. Borrow against the portfolio or sell something? Tell me what each option costs me, including the gains and the interest.”
- “My equity vests in March. I’ll be up six figures on paper and I’m already overweight my employer’s sector. What’s the tax-aware way to unwind that without wrecking my allocation?”
- “I have $50,000 to put to work. Taxable, Roth, or the rollover IRA, and in what order, given my bracket and what I’m already holding in each?”
- “Is my money working against itself anywhere? Two accounts doing the same job, or positions canceling each other out?”
- “Pay down the mortgage faster or invest the difference? Run it against my rate, my bracket, and my timeline.”
It shows its work, so you understand the why, not just the what. It remembers your goals, so you don’t start from scratch each time, and you control what it keeps.
It recommends, and you decide. It never moves your money on its own, and when you’re ready, you act right there in M1.
The wealthy have always had two things: an institution that handles the chores and an expert who sees the whole picture. Now you have both.
That’s the shift. You stop trying to keep up with your money and start putting it to work for the life you want.
Constantly getting better
Today is the starting line, just as 1976 was for the index fund. The AI models behind M1 Advisor are improving fast, and M1 clients benefit every time they do. We keep upgrading everything around those models too, with better instructions, more tools, and new capabilities.
Like wealth, those improvements compound. We’re building M1 Advisor to keep getting smarter, faster, and more capable. Picture what that means over a lifetime: an expert who knows your goals, grows with you, and gets better every year you work together.
M1 Advisor is free for M1 clients through 2027. If you’re an M1 client, log in and tap M1 Advisor.
New to M1? Clients already keep more than $14 billion at M1. Open an account at m1.com.
Log in and tap M1 Advisor to get started.

Brian Barnes Founder and CEO, M1
1Asset totals from the Investment Company Institute, *Active and Index Investing*, August 2026: $22.40 trillion in index mutual funds and index ETFs against $18.87 trillion in active, with index funds at 54.3% of the combined total. Expense ratios from ICI, *Trends in the Expenses and Fees of Funds, 2025*: an average of 0.64% for actively managed domestic equity mutual funds against 0.20% for index equity mutual funds. The annual figure applies that 44-basis-point difference to indexed assets and is an approximation, since the fee comparison is drawn from equity funds while the asset totals include bond and other categories.
Be sure to consider all your available options and the applicable fees and features of each before moving your retirement assets. A rollover is only one of your options for your retirement account, please see IRS guidance about rollovers for additional details/considerations.
Past performance is no guarantee future results. This is not an offer, solicitation of an offer, or advice to buy or sell any security and you are encouraged to consult your personal investment, legal, or tax advisors.
Utilizing the Moving Slices feature may cause trades to take place in other accounts you use the same Pie in. Please visit our article on Moving Slices when Pies are used in more than one account for further information.
Brokerage products and services are offered by M1 Finance LLC, Member FINRA / SIPC, and a wholly owned subsidiary of M1 Holdings, Inc.
Stated APY (annual percentage yield) with the M1 High-Yield Cash Account is accrued on account balance. APY is solely determined by M1 Finance LLC and its partner banks, and will include administrative and account fees that may reduce earnings. Rates are subject to change without notice. M1 High-Yield Cash Account is a separate offering from, and not linked to, the M1 High Yield Savings Accounts offered by M1 Spend LLC’s banking partner. M1 is not a bank.
If you choose to transfer your account to another broker-dealer, only the full shares are guaranteed to transfer. Fractional shares may need to be liquidated and transferred as cash.
M1 High-Yield Savings Accounts are furnished by B2 Bank, NA, Member FDIC (“B2”). M1 is not a bank. B2 Bank is a member FDIC institution and does not itself provide more than $250,000 of FDIC insurance per legal category of account ownership as described in FDIC regulations. Additional FDIC insurance coverage is provided through B2’s Insured Deposit Network Program involving other FDIC insured depository institutions. Deposits may be insured up to $5,000,000 through B2’s Insured Deposit Network Program. Full terms of the Program can be found at m1.com/legal/agreements/hysa_agreement and a complete list of participating banks in the program can be found at m1.com/legal/agreements/depositnetwork
All M1 clients have access to a single trading window each morning or afternoon. To participate in both trade windows, you must have $25,000 or more in equity to comply with pattern-day trading regulations.
Stock markets are volatile and can fluctuate significantly in response to company, industry, political, regulatory, market, or economic developments. All investing involves risks, including the loss of principal.
M1 and its affiliates do not provide tax, legal, or accounting advice. This material has been prepared for informational purposes only. It is not intended to provide, and should not be relied on for, tax, legal or accounting advice. You should consult your own tax, legal, and accounting advisors before engaging in any transaction.
M1 Finance, in its capacity as a brokerage firm, does not provide personalized investment, financial, legal, or tax advice in connection with this communication. Any securities or investment products mentioned are provided for informational purposes only and should not be considered a recommendation or a solicitation to buy or sell any security. You should consult your personal investment, legal, and tax advisors before making any investment decisions. Past performance does not guarantee future results.
SAIF-10012026-batzf6si
- Categories
- M1